NRIWallah team
Updated
October 2026
· 3 min read
Moving to India does not make you non-resident
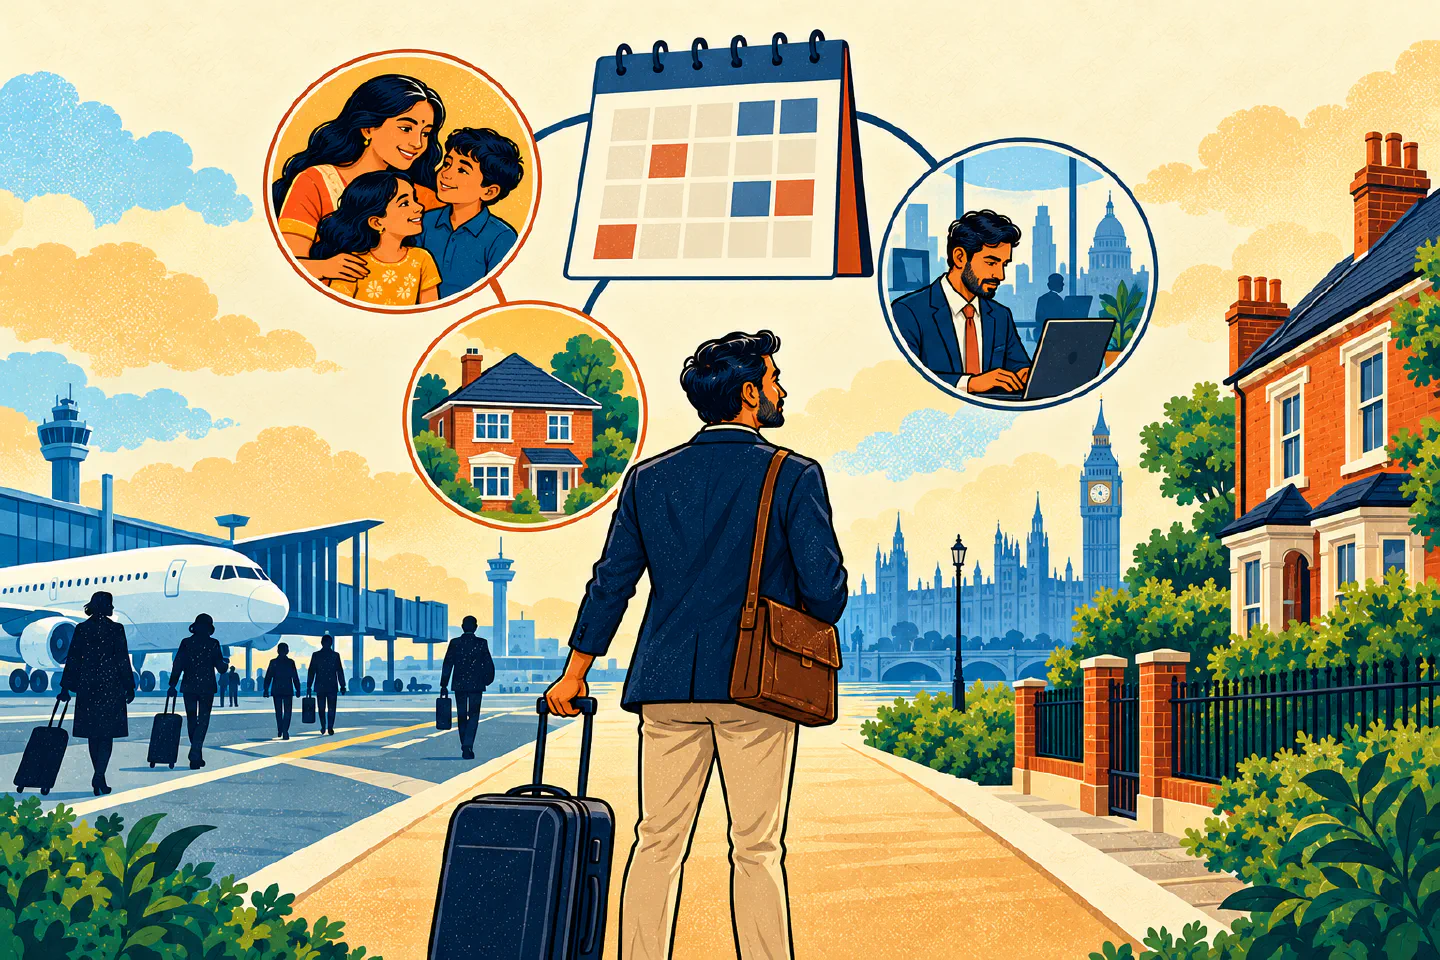
Much UK tax guidance, including the other calculators on this site, starts by assuming you know whether you are UK resident. Residence is not something you choose or declare. It is decided by a mechanical test of how many days you spent in the UK and what you kept there. Your visa and the place you tell people you are based do not enter into it.
Someone who moved to Bengaluru but kept a flat in Harrow, has children at school in Britain and returns for eight weeks a year can stay UK resident for years. UK tax is then due on their Indian salary and rent throughout.
The tests run in a fixed order
- Automatic overseas tests. Meet any one and you are non-resident. Nothing later can change that, whether a UK home, a UK job or five ties.
- Automatic UK tests. Reached only if no overseas test applied. Meet any one and you are resident.
- Sufficient ties test. Reached only if neither set has decided it.
Confusion usually comes from checking the UK tests first and concluding you are resident when an overseas test had already settled it.
The automatic overseas tests
There are three:
- You were UK resident in at least one of the previous three tax years and spend fewer than 16 days in the UK.
- You were resident in none of the previous three tax years and spend fewer than 46 days.
- You work full-time abroad, averaging at least 35 hours a week, and spend fewer than 91 days in the UK, of which no more than 30 are working days.
The day limit falls from 46 to 16 once you have been resident recently, which is about two weeks a year. One long family visit can use it. The third test is the one most working NRIs rely on, and both of its caps must hold.
The automatic UK tests
There are also three: 183 or more days in the UK in the tax year; your only home in the UK for 91 days or more in a row, with at least 30 days spent in it in the tax year; or full-time work in the UK over any 365-day period with at least one day in the tax year.
The home test catches NRIs who keep a UK flat before they have set up a home in India. It looks at your only home, so it can make you resident on a light day count. Once you also have a home in India, the test generally stops applying, provided you are present in the Indian home on at least 30 days in the year.
Ties trade against days
If neither automatic set decides it, the sufficient ties test balances days against ties. The more ties you keep, the fewer days you can spend. A leaver with four ties becomes resident at 16 days, and one with a single tie has until 120.
Leavers fall under Table A and arrivers under the more generous Table B. Identical facts can therefore give opposite answers depending on your history. The calculator above switches between the tables and highlights the row you land in.
Why it matters beyond this year’s tax
Each tax year you are UK resident counts towards the ten-of-the-last-twenty-years test for inheritance tax. Once you pass it, your worldwide estate, Indian property included, comes into UK charge at 40% for a period after you leave.
Someone who thinks they left in 2019 but was technically resident until 2022 is three years further along that clock than they believe. The inheritance and gift calculator covers what happens when it trips, and moving back to India covers how long it follows you. The NRI day tracker runs this test alongside India’s from one trip log.