IST: 00:00 PM
IST:
India bank holiday in 6 days: Diwali (Deepavali) (Sun, 8 Nov) See full calendar

All NRIs

TCS on money sent out of India

Tax collected at source applies to money leaving India under the Liberalised Remittance Scheme, not to money coming in.

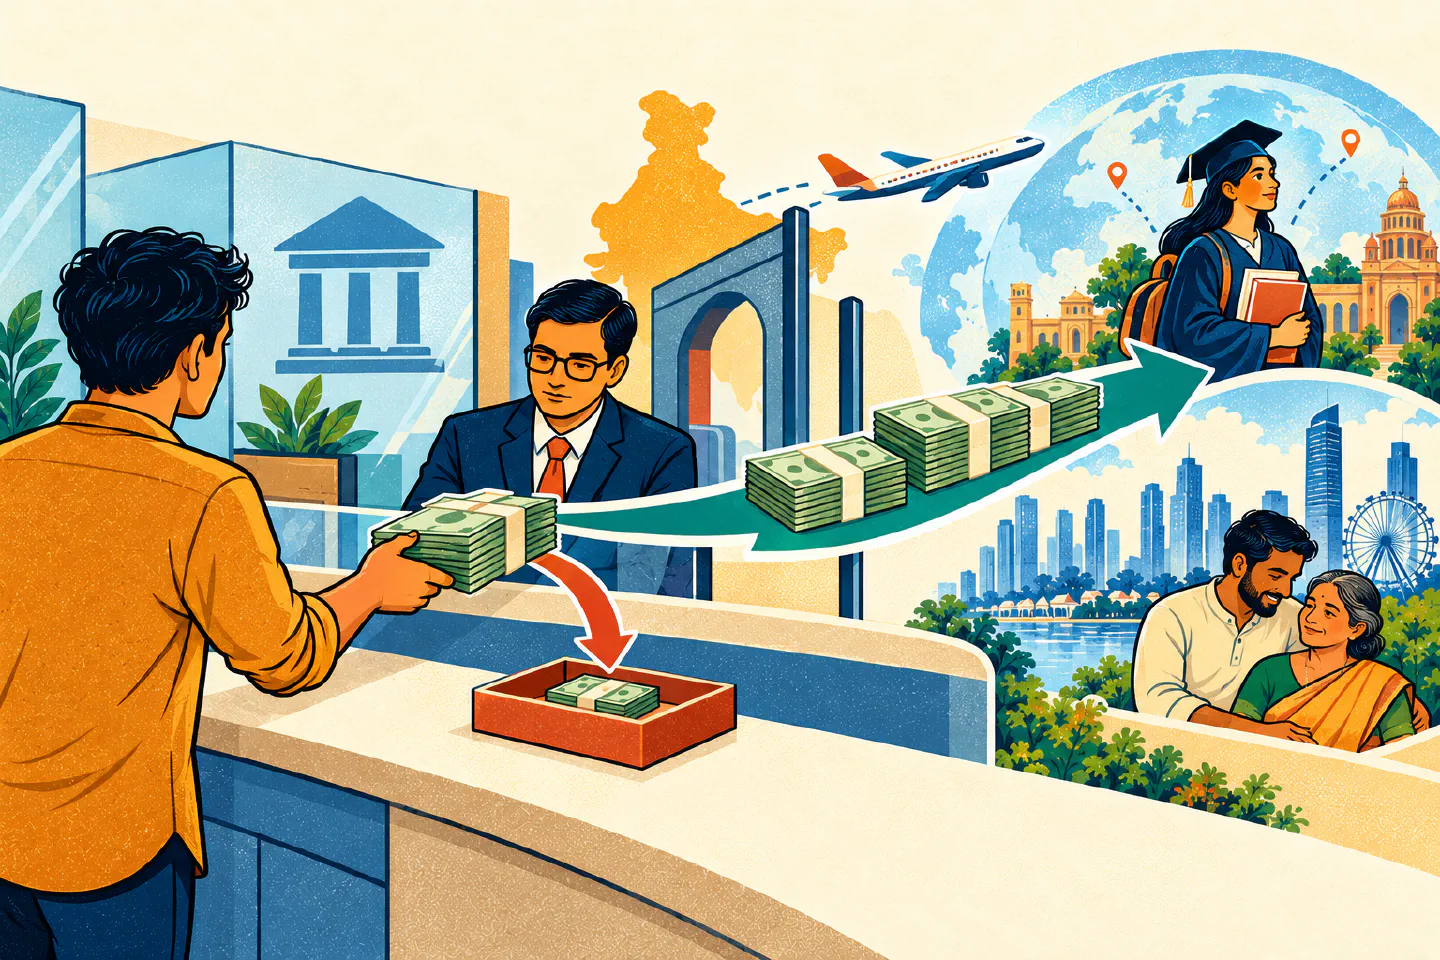
Illustration of money sent abroad under India's LRS with a portion withheld for tax

NRIWallah team

Updated October 2026 · 3 min read


There is no TCS on money coming into India

An NRI funding an NRE account, supporting parents, paying for a flat or repaying a loan sends money that arrives with nothing collected at source.

Tax collected at source applies to money leaving India under the Liberalised Remittance Scheme (LRS). It is section 394(1) of the Income-tax Act, 2025 from 1 April 2026, and was section 206C(1G) of the 1961 Act before that. The LRS is open only to individuals resident in India, so an NRI cannot use it and cannot fall within the section.

When it does affect an NRI

It applies in the other direction. Your parents in India sending you money abroad, a sibling gifting you funds, family paying your children’s overseas school fees and a resident relative buying foreign shares are all outward LRS remittances. Any of them can attract TCS.

It also applies to you personally once you move back and become resident again, as your own transfers out of India then fall inside the scheme.

The rates from 1 April 2026

Nothing is collected until aggregate remittances in the financial year pass ₹10 lakh. Above that:

  • Education or medical treatment: 2% of the excess (it was 5% until 31 March 2026)
  • Anything else: 20% of the excess
  • Education funded by a qualifying education loan: nil, whatever the amount

A family paying a degree fee of ₹25 lakh from savings is collected on ₹15 lakh at 2%, which is ₹30,000. The same fee paid from a loan under section 80E(3)(b) from a financial institution attracts nothing.

Overseas tour packages are a separate limb. From 1 April 2026 TCS is a flat 2% of the package price with no ₹10 lakh exemption. Before that it was 5% up to ₹10 lakh and 20% above. Flights and hotels booked separately are not a package and follow the ordinary LRS rules, so nothing is collected below ₹10 lakh.

Some summary pages and older guides still show the pre-April 2026 rates, so check the date on anything you read.

Splitting the transfer does not help

The ₹10 lakh threshold is an aggregate for the financial year across every bank you use, not a limit per transaction or per bank. Your bank collects a declaration of what you have already remitted elsewhere.

Two transfers of ₹8 lakh are therefore not two exempt transfers. The first is free, and the second is taxed on ₹6 lakh of its ₹8 lakh. For a non-education purpose that is ₹1,20,000, an effective 15% on the second transfer.

TCS is a prepayment, not a charge

The amount collected is deposited against your PAN, shows in your Form 26AS and Annual Information Statement and is set off against your income tax for the year. If your liability is lower than what was collected, the difference is refunded when you file.

The cost is the use of the money in the meantime. On a large remittance at 20%, that can be a substantial sum held for most of a year.

If you are the one receiving the money, nothing here applies to you, but gift tax in India might, depending on who sent it and whether they count as a relative under section 56(2)(x). Moving money out of an NRO account uses the USD 1 million route, which carries TDS under section 195 rather than TCS. The repatriation calculator covers it and the Form 15CA/15CB paperwork. If a return to India is planned, moving back to India covers when these rules begin to apply to you, and the 180-day rule explainer separates the FEMA and income-tax tests.
First, the direction — because most people have it backwards.

This transfer

Across every bank, April to March. This is the number that decides whether your exemption is still available.

What gets collected

Free of TCS (threshold left)
Taxable slice
Above the threshold Exempt — loan-funded
TCS collected
Effective rate on the transfer
Total leaving your account

After this you'll have of the annual exemption left.

This uses up your annual exemption. Everything else you send before 31 March is taxable from the first rupee.

Tour packages have no exempt slice — TCS starts at the first rupee.

This is not a cost

What this means

  • Of the you send, is collected on top, an effective . The purpose you declare to the bank decides the rate, so check it matches what the money is really for.
  • Nothing is collected on this transfer: it fits inside the annual exemption. Later transfers in the same financial year count against what is left of it.
The link holds the numbers above, so whoever opens it sees the same result. Saving keeps those numbers in your account.Nothing is stored by us.

Keep this result. An NRIWallah account saves it and sets NRIWallah up for where you live, so you don't type it all again.

Save it

The same , sent for a different reason

PurposeRateTCSvs your choice

The purpose you declare to your bank decides the rate, and you must be able to evidence it. Declaring education to get the lower rate on what is really a gift is a false declaration, not a strategy.

Splitting the transfer does not avoid it

Two transfers of are not two exempt transfers. The first is free; the second is taxed on of its — , an effective on that second transfer alone.

Two rules people still quote that no longer exist

Rates for FY , reviewed

Common questions


Yes. On a ₹25 lakh remittance, education or medical costs ₹30,000 and anything else costs ₹3,00,000, ten times as much for the same money. The purpose is declared to your bank and must be backed by documents. Describing a gift as education is a false declaration, not a planning technique.

If you are salaried, yes. Section 192(2B) lets you declare tax collected at source to your employer so it is set off against the TDS on your salary. The declaration is made on Form 12BAA, which has since been consolidated into Form 122. Otherwise you wait for the refund when you file.

Collection is at twice the normal rate, or 5%, whichever is higher. This is an edge case, because a resident remitting under the LRS almost always holds a PAN. Whether the higher rate can override the nil rate on loan-funded education remittances is unclear, so ask your bank what it will do before you remit.

Section 206CCA, which doubled the rate for people who had not filed returns, was omitted from 1 April 2025. Section 206C(1H), the 0.1% on sales of goods above ₹50 lakh, was withdrawn from the same date. The ₹7 lakh threshold and the 5% education and medical rate are also out of date.

They are the expected position, and the rates apply from 1 April 2026. Your bank is the collector, and what it charges depends on the purpose you declare, your documents and the total it computes from your declarations. Confirm with it before remitting a large sum.

Sending a large sum out of India?

If the amount is significant or the purpose is not clear-cut, the difference between 2% and 20% is worth getting right in advance. Tell us the shape of the transfer.

Something went wrong. Please try again in a few minutes, or reach us through our contact form.

Free to use. NRIWallah may receive a referral fee from the professional, never from you — how we make money.

Every rate and threshold here is sourced, dated and shown on the page — but tax rules change, and we would rather be told than be wrong. Reports go to the team that maintains the tool. If you can point at the official source, that gets it fixed fastest.

No account needed. We don't publish your email or add you to anything.

How we source and review these numbers is set out in our methodology.