NRIWallah team
Updated October 2026 · 5 min read
The buyer withholds tax on the full price
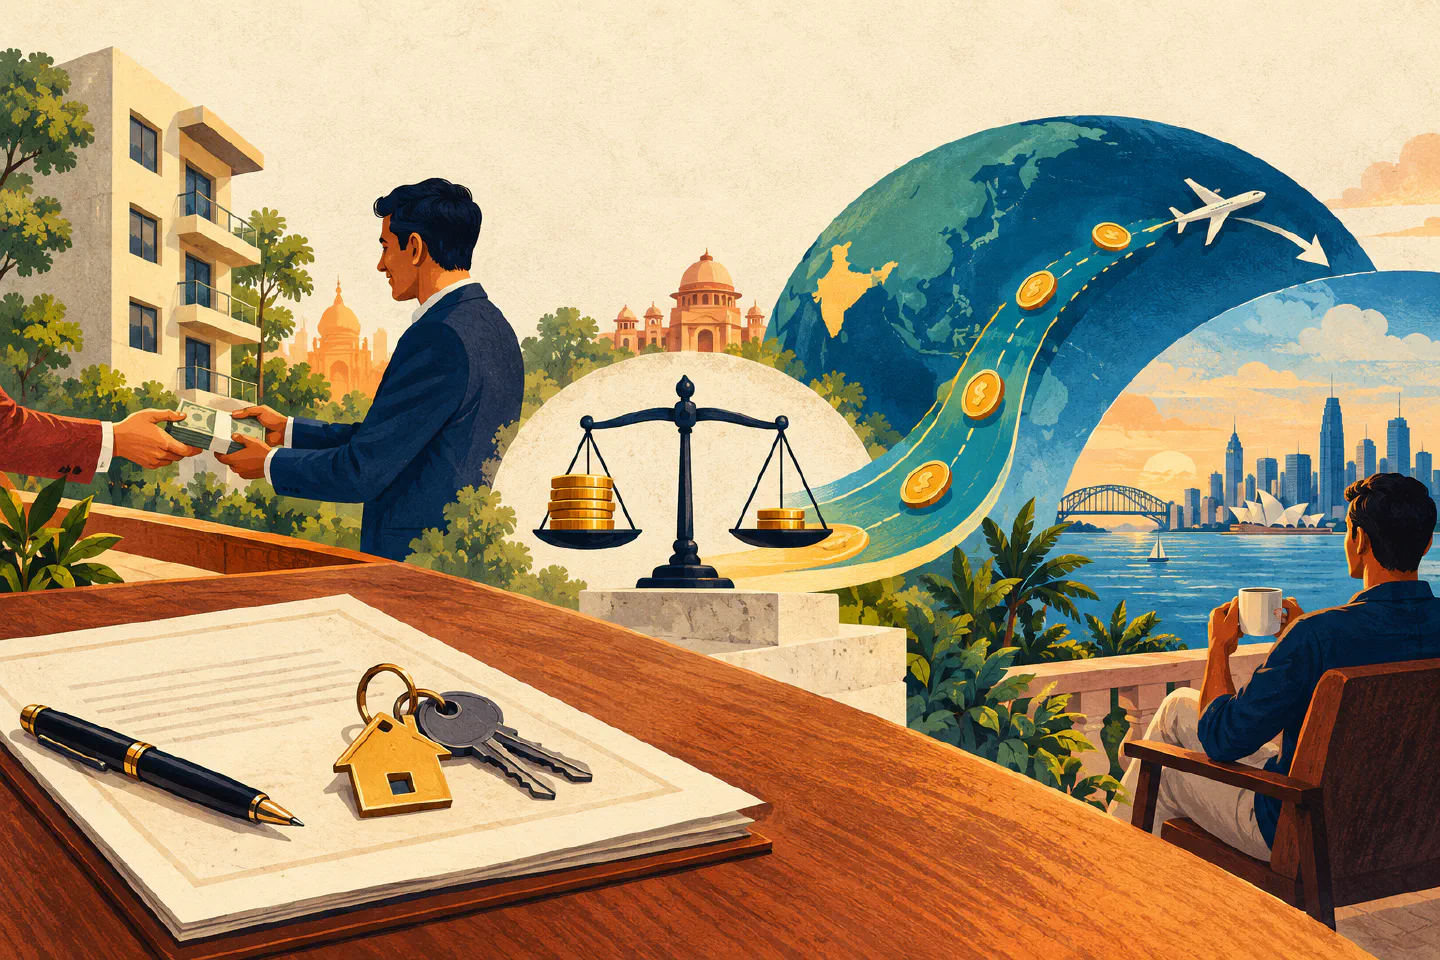
When a resident Indian sells property, the buyer deducts a nominal 1% TDS. When an NRI sells, the buyer must deduct tax on the full sale consideration at the rates for the seller’s capital gains, and the buyer is personally liable for getting it wrong. On a ₹2 crore sale that can mean ₹25-30 lakh withheld at source, even when your taxable gain is a fraction of that.
The money is not lost, because you reclaim any excess when you file your Indian return, but the refund can take a year or more. Two documents protect your cash flow: a lower-deduction certificate on Form 13, obtained before completion, and clean Form 15CA and 15CB filings when you move the proceeds abroad. The steps below cover both, with the capital gains arithmetic between them.
Step 1: know your holding period and rate
- Long-term (held over 24 months): gains are taxed at 12.5% without indexation, under the rules that apply from July 2024. TDS is deducted at that rate plus surcharge and cess on the whole sale price, which comes to roughly 13-15% of the price.
- Short-term (24 months or less): gains are taxed at your slab rate, and TDS is 30% or more of the sale price.
- Inherited property: your holding period includes the previous owner’s, and their cost becomes your cost. Most inherited sales are long-term.
The buyer needs a TAN, must deposit the TDS and must give you Form 16A. Many resident buyers have never done this, and sales to NRIs can stall over it, so raise it early in negotiations. A buyer who deducts 1%, as for a resident seller, has under-deducted. The shortfall is recoverable from the buyer, which is the kind of dispute that can hold up registration.
Step 2: apply for a lower-deduction certificate
This is the highest-value step for an NRI seller. You, usually through a chartered accountant, file Form 13 online with the jurisdictional assessing officer, showing the expected sale price, your cost and the resulting gain. The officer issues a certificate telling the buyer to deduct TDS at a rate matched to your actual liability. The Form 13 guide covers documents, timelines and common reasons for rejection.
Certificates take several weeks, name the specific buyer and are valid for the financial year. Apply as soon as a buyer is identified and before the final sale deed is signed.
Step 3: reduce the gain itself
Two main exemptions can bring the gain down:
- Section 54: reinvest the gain in another residential property in India, bought one year before or two years after the sale, or built within three years.
- Section 54EC: invest up to ₹50 lakh of the gain in specified bonds (NHAI or REC) within six months, with a five-year lock-in.
Both apply to NRIs, and both need the investment to be in India. Buying a house in London or Dubai does not qualify. If you plan to claim them, say so in the Form 13 application, since the certificate can then reflect a near-zero rate.
Step 4: repatriate the proceeds
Sale proceeds go to your NRO account. The repatriation calculator shows the caps and paperwork. In short:
- Up to USD 1 million a financial year can move abroad from NRO funds, with Form 15CA (your declaration) and Form 15CB (a chartered accountant’s certificate that tax has been paid).
- If you bought the property with NRE or FCNR funds, the original foreign-currency purchase amount can be repatriated outside the cap, for up to two residential properties.
- Your bank’s remittance desk runs the process, and a CA who has handled 15CB for property sales can save weeks.
When the funds are ready, compare the remittance corridors. On a transfer of this size, the difference between a margin of 0.2% and 2% is a large sum.
Step 5: your home country
If you are tax-resident in the US, UK, Canada or Australia, the gain is usually reportable there as well, with a foreign tax credit for the Indian tax under the treaty. The UAE and Singapore generally do not tax it. The DTAA estimator runs the numbers.
Your home country may compute the gain in its own currency from the original purchase date, which can produce a taxable gain, or a loss, even when the rupee gain is small. US sellers must also remember FBAR and FATCA reporting once the proceeds sit in Indian accounts, covered in the US NRI hub.
Where sellers lose money
- No Form 13. About 13-15% of the sale value is locked up for a year as a refund claim.
- Proceeds left idle in NRO. Interest on NRO deposits is taxed in India at 30% or more. Repatriate within the limit, or accept that money kept in India earns taxable interest. Our FD rate comparison shows current rates.
- Selling inside 24 months. Waiting a few weeks to cross the long-term threshold can halve the tax.
- Do-it-yourself 15CA and 15CB. Banks return imprecise filings, and each return costs weeks.
This guide is general information, not tax advice. Rules are current for FY 2025-26 and change with each Budget. For your own sale, use the form on this page to speak to a qualified professional. NRIWallah may receive a referral fee from the professional, never from you (how we make money).