IST: 00:00 PM
IST:

All NRIs

TDS on rent paid to an NRI landlord

Tax of 31.2% is withheld on gross rent with no threshold, but you owe tax on a much smaller figure.

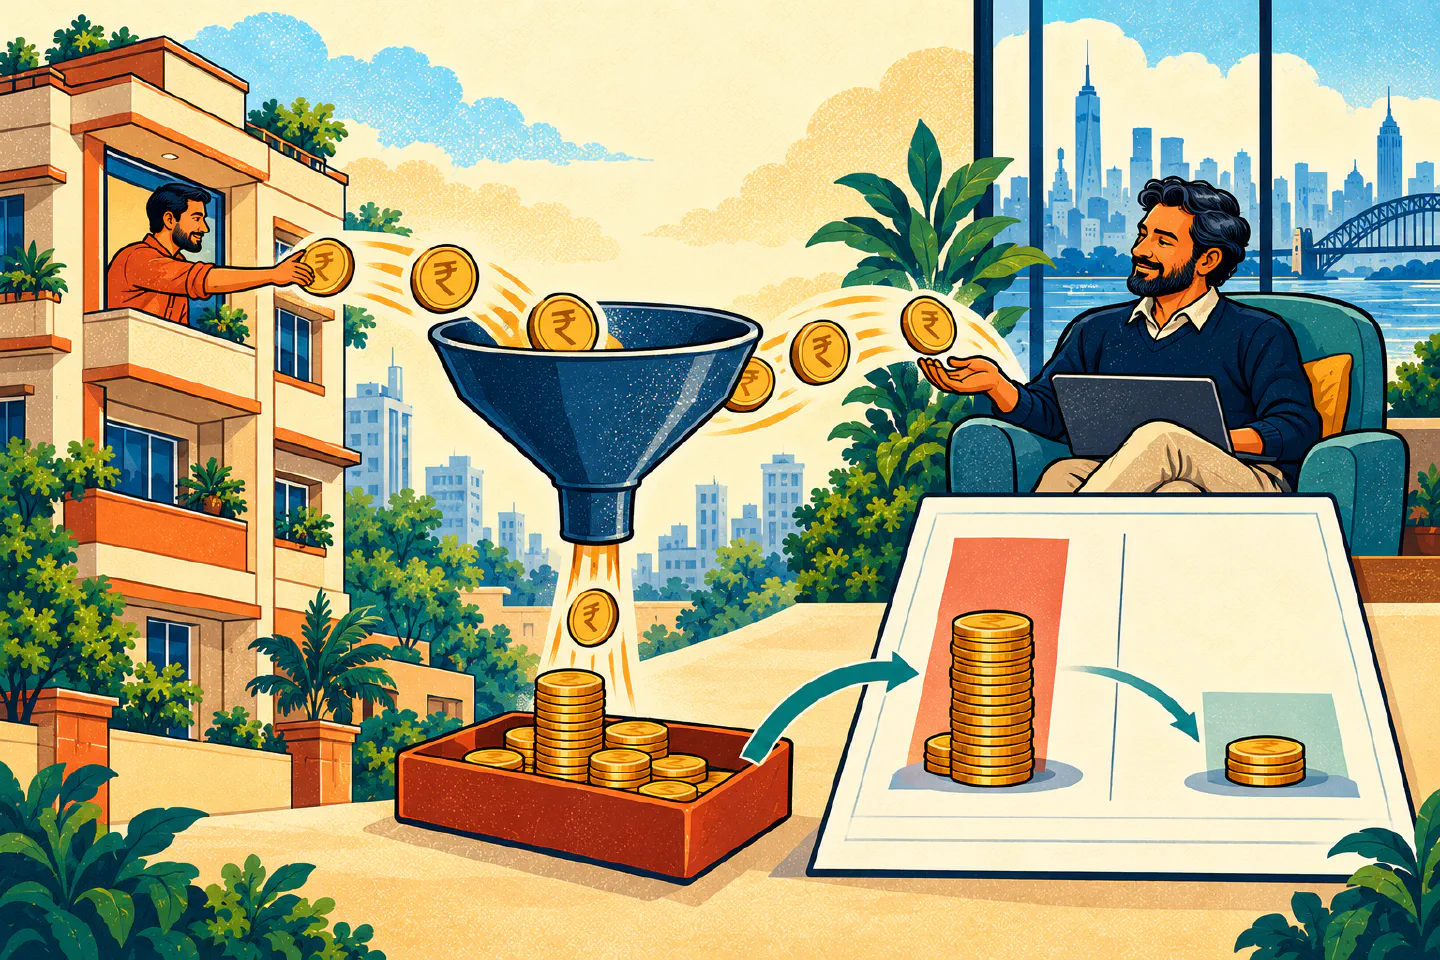
Illustration showing rent from an Indian property split between tax withheld and a landlord abroad

NRIWallah team

Updated October 2026 · 3 min read


Why the ₹50,000 threshold does not apply

TDS on rent starts at ₹50,000 a month only when an individual pays rent to a resident landlord. That limit sits in section 194-IB. A second limit of ₹6 lakh a year, raised from ₹2.4 lakh on 1 April 2025, sits in section 194-I and covers businesses paying rent to residents.

When the landlord is a non-resident, both provisions fall away and section 195 applies. From 1 April 2026 the same rule is section 393(2) of the Income-tax Act, 2025, with the substance unchanged. Section 195 has no threshold, so a tenant paying ₹8,000 a month to an NRI landlord must deduct 31.2% just as one paying ₹80,000 must. The tenant deposits it monthly and files a quarterly return.

Why the withholding is far above the tax

The 31.2% is charged on gross rent. Your liability is charged on income from house property: gross rent, less municipal taxes you paid, less a flat 30% standard deduction, less interest on any loan against the property.

Take ₹50,000 a month with no municipal taxes and no loan. Gross rent is ₹6 lakh a year, so ₹1,87,200 is withheld. The 30% deduction brings the taxable figure to ₹4.2 lakh. After the ₹4 lakh basic exemption under the new regime, ₹20,000 is taxed, which comes to about ₹1,040 with cess. The withholding is roughly 180 times the tax, and the difference stays with the government until you file and claim it.

The ₹12 lakh rebate is for residents only

The “no income tax up to ₹12 lakh” headline from the 2025 Budget is the rebate under section 87A, which is section 156 in the new Act. Only residents can claim it.

As an NRI you keep the ₹4 lakh basic exemption, but nothing cancels the tax above it. A resident with ₹12 lakh of income pays nothing. An NRI with the same ₹12 lakh pays about ₹62,400 (as of FY 2026-27).

Two ways to close the gap

The slow way is to reclaim the excess by filing ITR-2 after the year ends, reporting the rent under income from house property and taking credit for the TDS.

The faster way is to prevent the over-deduction. A Form 128 application (formerly Form 13 under section 197) asks the assessing officer to certify a lower rate that reflects what you will actually owe, and your tenant then deducts at that rate. Apply before the financial year begins. The certificate takes weeks, is not backdated and names a specific payer, so a new tenant needs a new application. The same mechanism applies when you sell Indian property, where the sums are larger, and the lower TDS certificate guide explains the process.

Tax where you live

The rent is usually taxable again in your country of residence. A double-taxation treaty then gives credit for the Indian tax, and you will need Form 131 and your Indian return as evidence. The DTAA estimator shows how the same Indian income is treated in the main NRI destinations, and the repatriation calculator covers sending the money out under the USD 1 million annual limit.

NRIWallah does not provide tax advice. Figures are estimates for FY 2026-27 (AY 2027-28) under the default new regime and assume a single let-out property. Take professional advice before acting.
The rule most people get wrong. The ₹50,000-a-month threshold you may have read about is section 194-IB, and it only applies when the landlord is a resident. Rent paid to an NRI falls under section 195 (renumbered 393(2) from 1 April 2026), which has no threshold at all — 31.2% is due from the first rupee, on residential and commercial property alike. Meanwhile your actual tax is charged on a much smaller figure. This works out both.

The rent

Typically 5–10%. This does not reduce the TDS base — see below.

Your Indian tax position

Property tax actually paid by you, not by the tenant. Deductible in full.

Interest only, not the principal. Deductible in full on a let-out property.

NRO interest, dividends, pension. Rent stacks on top of these for slab purposes.

What gets withheld vs what you actually owe

TDS withheld over the year

Tax you actually owe

on taxable income of

Locked up as a refund claim

What this means

  • Of the rent, about reaches you each month; the tenant pays the rest to the tax department in your name.
  • As a tax resident of the , you will usually declare this rent there too. Claim credit there for the tax you finally owe in India, not the larger amount withheld.
  • The doesn't usually tax an individual's Indian rent, so India's figure is what counts.
The link holds the numbers above, so whoever opens it sees the same result. Saving keeps those numbers in your account.Nothing is stored by us.

Keep this result. An NRIWallah account saves it and sets NRIWallah up for where you live, so you don't type it all again.

Save it

Agent commission and TDS

Your manager collects the rent, keeps a commission and remits the rest. The TDS is still due on the full rent the tenant pays, not on what lands in your account — the commission is an application of your income, not a reduction of it. Agents who compute TDS on the net figure under-deduct every month.

Rent collected from the tenant
Less manager's commission ()
Remitted to you
TDS correctly computed on gross
TDS wrongly computed on the net
Shortfall if they get it wrong

You also cannot claim the commission as a separate expense. The 30% statutory deduction below is what covers management and maintenance — it is a flat allowance, not a reimbursement, so you take the 30% whether your actual costs are higher or lower.

How the TDS is built up

Deducted on
Base rate30%
Basic tax
Surcharge ()
Health & education cess (4%)
Withheld over the year
Per month

Rent above ₹50 lakh a year picks up surcharge, pushing the withholding rate past the usual 31.2%.

How your actual tax is worked out

Gross annual rent
Less municipal taxes
Net annual value
Less 30% statutory deduction
Less home loan interest
Income from house property
Plus other Indian income
Total taxable income
Tax at slab rates + cess

Your interest exceeds the rental income by . Under the new regime a loss from house property cannot be set off against your other income, so it is shown as nil rather than as relief.

A resident with your exact income would pay . You pay . The difference is the section 87A rebate — renumbered section 156 under the Income Tax Act 2025 — which is available only to residents. This is why the widely-quoted "no tax up to ₹12 lakh" headline does not reach you: you still get the ₹4 lakh basic exemption, but not the rebate that wipes out the tax above it.

Who has to do what

The payer's checklist, every month:

  1. Obtain a TAN — a PAN is not enough, and Form 26QC (the resident route) is not available here
  2. Deduct of the gross rent — a month on these figures
  3. Deposit it by the 7th of the following month
  4. File Form 27Q quarterly
  5. Issue you Form 131, so you can claim the credit

Getting this wrong makes the payer — not you — an assessee-in-default under section 201, with interest and penalty on top of the tax.

Route 1 — claim it back afterwards

File ITR-2 after the financial year ends. Check the TDS appears in your Form 26AS and AIS, claim the credit, and nominate a pre-validated NRO account for the refund.

You recover
Wait12–18 months

Interest-free to you for the whole period.

Route 2 — stop it at source

Apply on Form 128 (formerly Form 13 under section 197) before the year starts. The officer certifies a rate matching your real liability and your payer deducts that instead.

Withheld instead
WaitNone

Certificate is payer-specific, so reapply if your tenant changes.

What actually happens in practice. Plenty of NRI landlords have let property for years with no TDS deducted and never heard from anyone. That is not evidence the rule is different — it reflects two things. First, the obligation sits with whoever pays you, so you were never the party in breach; if you declared the rent and paid the tax, your own position is straight. Second, a payer who never deducts also never obtains a TAN or files a Form 27Q, so nothing enters the system to mismatch against. Enforcement concentrates where the paperwork exists: business tenants, whose auditors reconcile rent paid against TDS deducted and who lose the deduction for rent paid to a non-resident without it. Worth knowing rather than worrying about — but if no TDS is being deducted, make sure the tax is going in as advance tax, or interest under sections 234B and 234C can follow.

Estimates for FY 2026-27 (AY 2027-28) under the default new regime, whose slabs are unchanged from FY 2025-26. Assumes a single let-out property and that the rent is your only Indian income beyond anything entered above. Excludes any tax due where you live — the same rent is usually taxable there too, with credit for Indian tax under the relevant double-taxation treaty. Not tax advice; confirm your position with a qualified adviser before relying on it.

Common questions


No. The residential and commercial distinction (10% on buildings, 2% on plant and machinery) sits in section 194-I, which covers resident landlords. For a non-resident landlord, section 195 applies one rate whatever the property or tenant. Above ₹50 lakh of rent a year, surcharge pushes the effective rate above 31.2%.

Whoever pays you. If the manager collects from the tenant and remits to you, the duty falls on them, and they should deduct on the gross rent the tenant pays, not on the amount after their commission. You cannot claim the commission as a separate expense, because the 30% standard deduction already covers management and maintenance.

The duty to deduct is the payer’s, so a tenant who never deducted is the party in breach. If you declared the rent in an Indian return and paid the tax, your own position is generally protected. A business tenant is the usual place the gap surfaces, because it loses the rent deduction without TDS. Your own exposure is interest under sections 234B and 234C if the tax was due as advance tax and you paid it only at filing.

File ITR-2 after the year ends and check that the TDS shows in your Form 26AS and AIS. If the tenant deducted but never filed Form 27Q, the credit will not appear, so ask for Form 131 (formerly Form 16A). Nominate a pre-validated NRO account for the refund, as an unvalidated one is the usual reason refunds stall. Expect twelve to eighteen months.

They become an assessee in default under section 201. The tax can be recovered from them with interest under section 201(1A) and a penalty under section 271C equal to the tax not deducted. A business tenant also loses the rent as an expense. None of this falls on you, but it is worth telling a tenant who does not know.

Talk to an NRI tax CA

Get matched with a chartered accountant who handles NRI rental income, Form 128 (formerly Form 13) applications and ITR-2 filing, free and with no obligation.

Something went wrong. Please email admin@nriwallah.com directly.

Free to use. NRIWallah may receive a referral fee from the professional, never from you — how we make money.

Every rate and threshold here is sourced, dated and shown on the page — but tax rules change, and we would rather be told than be wrong. Reports go to the team that maintains the tool. If you can point at the official source, that gets it fixed fastest.

No account needed. We don't publish your email or add you to anything.

Prefer email? admin@nriwallah.com. How we source and review these numbers is set out in our methodology.