NRIWallah team
Updated October 2026 · 4 min read
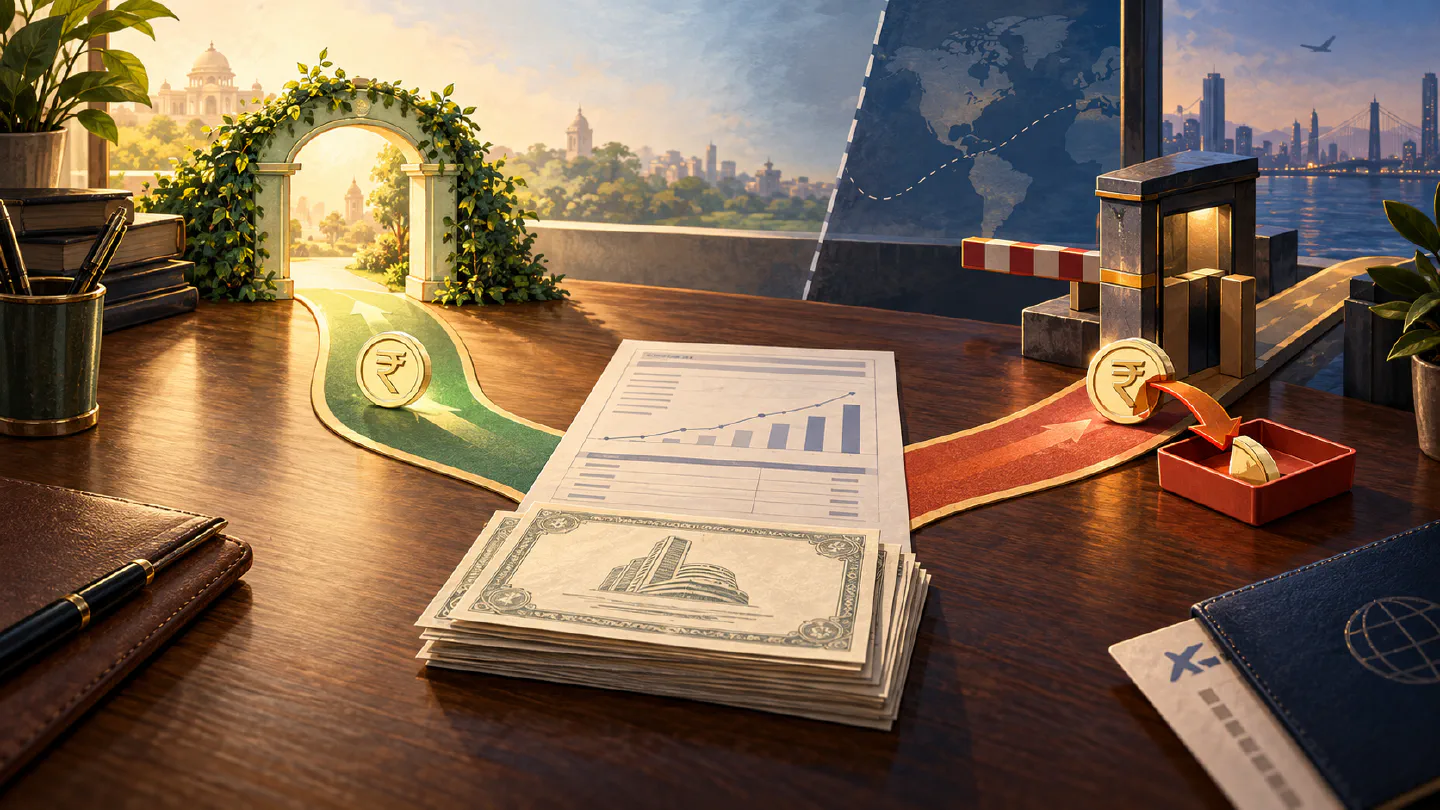
An NRI cannot use the basic exemption limit to reduce tax on capital gains that are taxed at special rates. A resident can. For FY 2026-27, that difference can turn a nil bill into one of tens of thousands of rupees on a fairly small gain.
What the basic exemption is
The basic exemption limit is the slice of income on which no tax is due. For FY 2026-27 it is ₹4 lakh under the new regime and ₹2.5 lakh under the old regime. NRIs and residents both have it.
It works on income taxed at ordinary slab rates. Capital gains taxed at special rates follow a different route, and that is where the two groups part.
Why you may have heard ₹12 lakh
The figure of ₹12 lakh is not the basic exemption. It is the income level up to which a resident pays no tax under the new regime, because a rebate under section 87A cancels the tax. The rebate is for resident individuals, so an NRI does not get it, and it cannot be set against gains taxed at special rates. For an NRI the tax-free slice stays ₹4 lakh.
Residents can set unused exemption against some gains
If a resident’s other income falls short of the limit, the unused part can be set against gains taxed at special rates. That covers:
- Short-term gains on listed shares and equity funds, taxed at 20% for sales on or after 23 July 2024.
- Long-term gains on listed shares and equity funds, taxed at 12.5% above ₹1.25 lakh.
- Long-term gains under the general long-term rule, such as those on property, taxed at 12.5%.
A retired resident with a small pension can therefore sell shares worth a few lakh of gain and owe nothing.
NRIs are taxed from the first rupee
The relief is limited to resident individuals. For an NRI, gains of these kinds are taxed from the first rupee, however little other income there is. The restriction sits in the long-term and short-term gain rules themselves, and it applies under both regimes.
Since 1 April 2026 the Income-tax Act, 2025 has replaced the 1961 Act with the same substance but renumbered sections, so older references may not match current forms.
A worked example
This is illustrative only, for FY 2026-27 under the new regime. It assumes no other income and ignores surcharge, treaty relief and any rebate.
| Resident | NRI | |
|---|---|---|
| Long-term gain on listed shares or an equity fund | ₹3,00,000 | ₹3,00,000 |
| Exempt first | ₹1,25,000 | ₹1,25,000 |
| Gain left to tax | ₹1,75,000 | ₹1,75,000 |
| Unused basic exemption of ₹4 lakh | Covers it | Not available |
| Tax at 12.5% | Nil | ₹21,875 |
| Cess at 4% | Nil | ₹875 |
| Tax payable | Nil | ₹22,750 |
The gain and the facts are the same. Only the residence status changes the answer.
In practice, an NRI planning to sell shares or fund units should expect tax on the whole taxable gain, and should budget for it before selling rather than assume the exemption will absorb it.
What an NRI keeps
The basic exemption still applies to an NRI’s income at slab rates. That means rent, interest and short-term gains that are taxed at slab rates. If your slab-rate income is below the limit, you pay no tax on it. The unused part does not carry over to a special-rate gain, so a low-income year does not help the way it helps a resident.
Nothing cancels the tax above the limit, though. The NRI rent TDS calculator shows the same pattern on rent: the exemption is kept, but it does not wipe out the tax on the rest.
TDS is deducted regardless
When an NRI sells, the buyer or payer deducts TDS on the gain or on the sale value, whatever the exemption. On a property sale that can lock up a large sum, as the property sale TDS guide explains.
Any excess is reclaimed by filing an Indian return, which can take months. For property, a lower TDS certificate on Form 13, obtained before completion, asks the assessing officer to set a rate that matches your actual liability.
Residence and treaties
Whether you are an NRI for the year depends on the days you spend in India. Count them with the NRI day tracker rather than estimating, because the answer decides which rules apply to your gain.
Indian tax paid on a gain may earn a credit in the country where you live. Treaty relief is covered in the DTAA estimator.
General information, not tax or investment advice. Rates, exemptions and section numbers change, and your position depends on your facts and your residence for the year. Consult a qualified tax adviser.