IST: 00:00 PM
IST:

UAE NRIs

The 180-day rule on overseas funds, explained for UAE NRIs

It is a real FEMA rule for residents of India who send money abroad, and it does not apply to salary you earn and hold in the UAE.

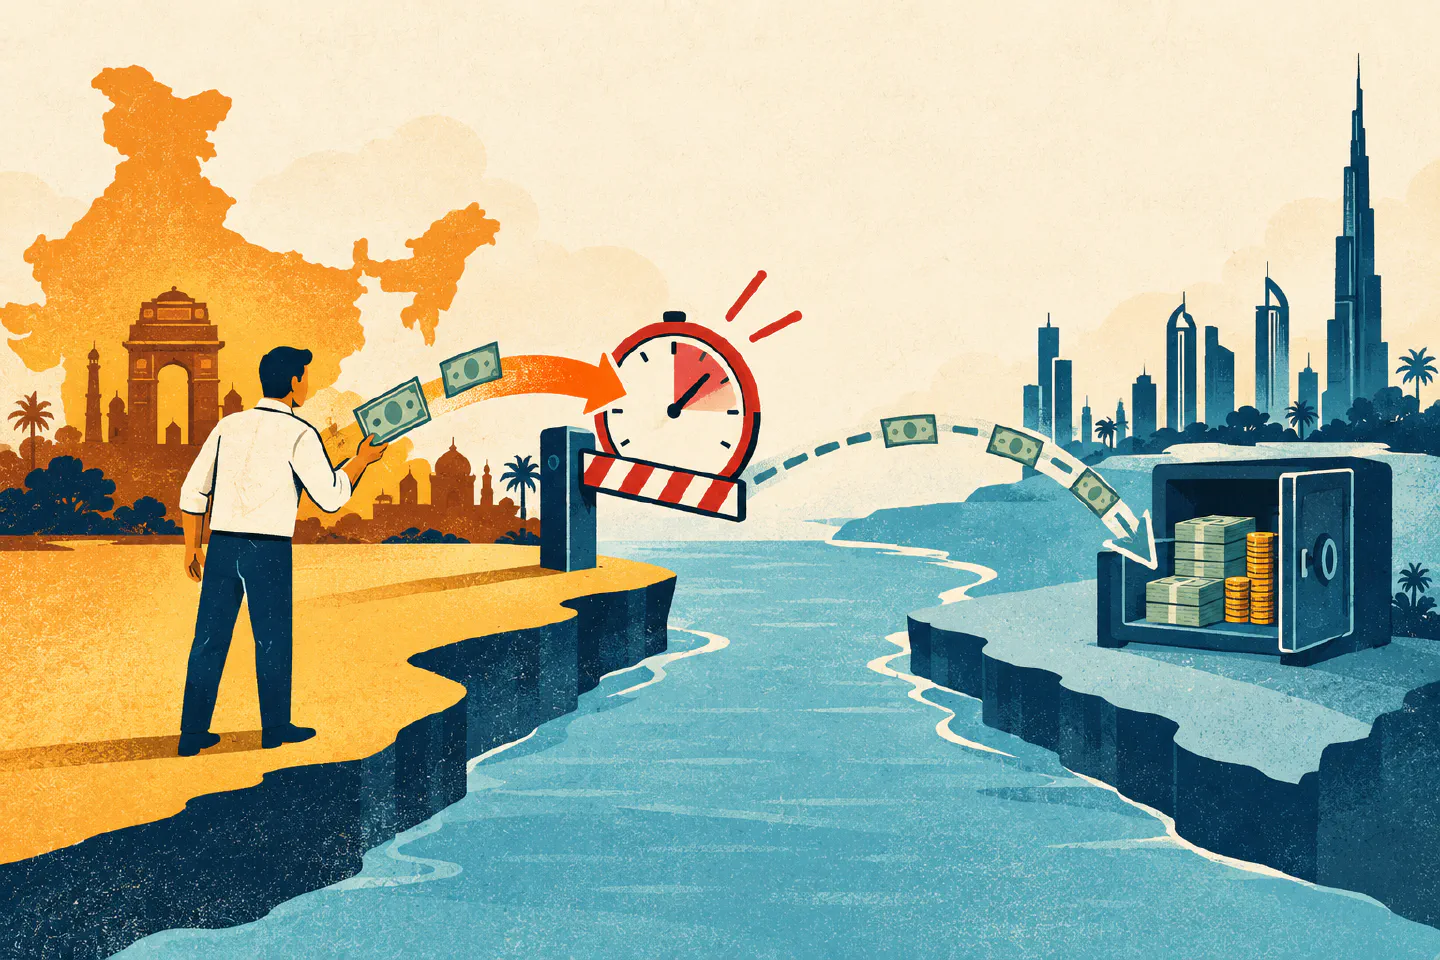
Editorial illustration of money moving between India and the UAE with a clock and a barrier

NRIWallah team

Updated October 2026 · 2 min read


What the rule is

The Liberalised Remittance Scheme (LRS) lets a resident of India send up to USD 250,000 a year abroad. If that money is not spent, invested or brought back within 180 days of being remitted, it is treated as idle foreign exchange and must be brought back or put to use. The rule is not new.

Press coverage of it was prompted by reports that some offshore private banks had begun refusing or restricting international cards for wealthy Indian residents, because they did not want to facilitate funds sitting idle past 180 days. That is a compliance story about residents of India moving money out, and about foreign banks tightening their own checks. A headline that reduces it to an “overseas funds rule” reads as if it could apply to any NRI with money outside India, and it does not.

Why 180 is confused with 182

India has a separate day count that decides your tax status. If you spend fewer than 182 days in India in a financial year, you are generally an NRI for income tax purposes, subject to conditions. That test sits in the Income Tax Act, measures where you were, and decides whether India taxes your worldwide income or only your Indian income.

The 180-day rule sits in FEMA and measures where money went. A UAE NRI passes the tax test by living outside India, and the FEMA rule never engages, because the money in question was never remitted out of India under the LRS.

When it could reach you

The route is moving back to India and becoming resident again. After that, fresh outward remittances for foreign shares, a child’s overseas education beyond immediate needs or offshore property fall under the LRS and the 180-day clock. The TCS guide covers the tax collected on those remittances. Until then, if you are a UAE-based NRI sending money in the other direction, none of this applies.

NRIWallah does not provide financial or legal advice. This explainer reflects our reading of the FEMA Liberalised Remittance Scheme rules and press coverage as at October 2026. Confirm your position with a qualified adviser, particularly if you plan to move back to India.

Common questions


No. The rule covers “persons resident in India” under FEMA, and an NRI is usually also non-resident under FEMA, which has its own test of residence (broadly, living outside India for employment, business or an indefinite stay). Money you earned and hold in the UAE was never remitted out of India under the LRS, so no 180-day clock is running on it.

No. The 182-day count is an Income Tax Act test of whether you are resident in India for tax. The 180-day rule is under FEMA and concerns how long money that has already left India can sit abroad unused. Your FEMA residence status is a separate test as well. The NRI day tracker counts the tax days trip by trip.

Only if you move back to India and become resident again, and then send fresh money abroad, for example to buy foreign shares or property. That outward remittance falls under the LRS and the 180-day clock starts. Sending money into an NRE, NRO or FCNR account, buying Indian property or repatriating money out of India all run under separate rules.