IST: 00:00 PM
IST:
India bank holiday in 7 days: Diwali (Deepavali) (Sun, 8 Nov) See full calendar

All NRIs

Retire in India

You save in one currency and will spend in another for thirty years. What that means for the corpus you need.

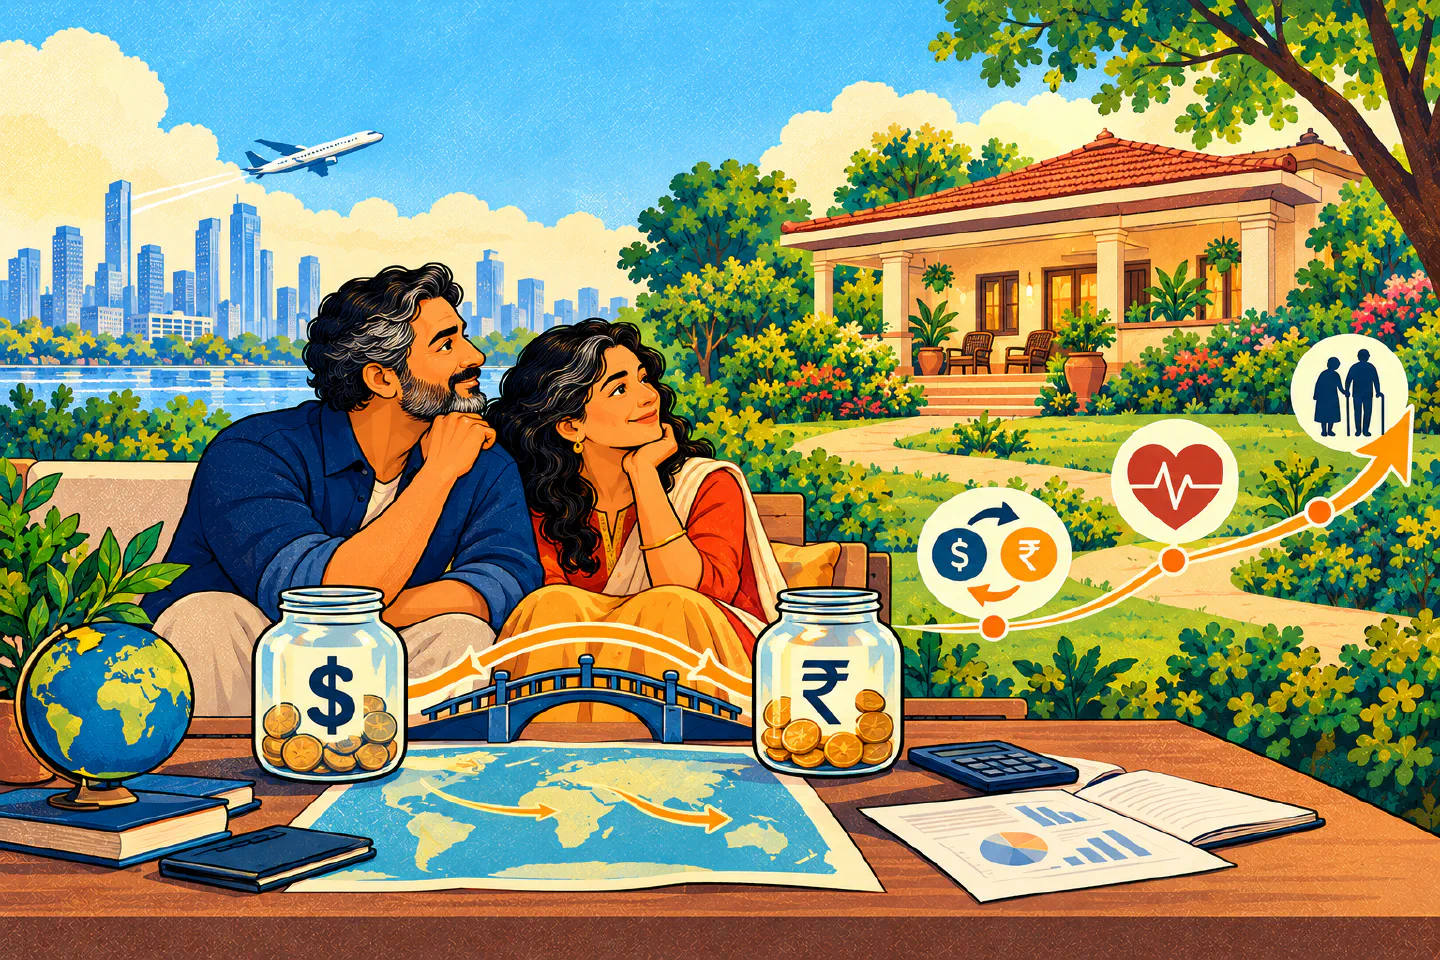
Illustration of a couple planning retirement in India with savings, currency and healthcare in view

NRIWallah team

Updated September 2026 · 3 min read


Indian retirement calculators assume you saved in rupees and will spend in rupees. As an NRI you have probably saved in pounds, dollars or dirhams for fifteen or twenty years and will spend in rupees for thirty more, across an exchange rate that moves throughout and two different inflation rates. This calculator models both sides.

The figure you need to fund

Ask what a comfortable Indian retirement costs and most people give a figure in today’s money: ₹1 lakh a month, perhaps ₹1.5 lakh for a couple who want to travel. At 6% inflation, ₹1.2 lakh a month today becomes about ₹3.85 lakh a month in twenty years, for the same way of life, and it keeps rising for the thirty years you draw on it. That is why the corpus runs into crores.

The most common error is to start inflating from the retirement date instead of from today, which leaves out twenty years of price rises.

Healthcare rises faster

Ordinary spending, on food, utilities, household help, travel and family obligations, rises at roughly 6% a year in the model. Health costs rise faster. Premiums for over-sixties rose so quickly that in January 2025 the insurance regulator told insurers not to raise senior citizens’ premiums by more than 10% a year. At 10% against 6%, healthcare’s share of your budget roughly doubles over thirty years, and it grows fastest when you can no longer earn more.

The falling rupee is not free money

Money kept abroad buys more rupees as the rupee falls. But the rupee falls largely because Indian inflation is higher than inflation abroad, and that same inflation raises the prices you will pay. Measured by what it buys in India, a 6% return in pounds with the rupee falling 2% a year comes to about 2% a year; a 9% return in rupees against 6% inflation comes to about 2.8%.

They are close, so whether to keep money abroad or bring it home should depend on currency risk, tax on each side, repatriation rules and how much Indian market volatility you want in your seventies, rather than on the exchange rate.

Tax when you return

Your NRE interest becomes taxable once you return to live in India. But people returning after a long time abroad are usually resident but not ordinarily resident (RNOR) for two or three financial years, when foreign income stays outside Indian tax. Selling foreign assets during that window rather than after it can make a large difference to the tax, so take cross-border tax advice before you time a sale. The RNOR tracker works out how long yours lasts, and moving back to India covers what the country you are leaving may charge; for Canadian and Australian residents that bill arrives before you have spent a rupee.

How far to trust the result

The arithmetic is exact, but the inputs are thirty-year guesses, and small changes move the answer a lot. The defaults lean cautious, with returns towards the low end, inflation towards the high end and the currency trend rounded down, so the model tends to tell you to save more. Treat the result as a sense of scale and revisit it every few years.

Two things to settle alongside the corpus. The city matters: cost of living compare puts Mumbai about 46% above Kochi for the same standard of living. And if children still have university ahead, the degree cost planner prices that claim on the same savings.
Why an Indian retirement calculator gets this wrong for you. It assumes you save rupees and spend rupees. You do neither — you accumulate in and will spend in rupees, across a gap that moves. And it inflates your whole budget at one rate, when the largest line in a retired household's spending, healthcare, compounds at 10% while the rest compounds at 6%.

Your timeline

Indian life expectancy at 60 is around 18 more years, but that is an average across the whole population. Planning to 90 is the sensible default for a well-off household with access to private healthcare — running out at 85 is a far worse error than dying with money left.

Saving where you live

Include pension pots, 401(k)/IRA, ISAs and taxable accounts — everything you would eventually bring across or draw on.

Saving in India

NRE and FCNR deposits, mutual funds, EPF, and any property you would let out. Exclude the home you will live in — it pays no income.

What retirement costs

Everything except healthcare — food, utilities, help, travel, and the family obligations that do not stop when you retire. In today's rupees; the model inflates it for you.

Pension from abroad

A UK State Pension is frozen for pensioners resident in India — there is no uprating agreement, so it never rises again from the day you leave. Untick the box if that applies to you; over thirty years it removes roughly half the pension's real value.

Long-run drift, rounded down.

is the corpus you need, in the rupees of that day.

On your current saving you are projected to have

You are ahead by .

Short by — closed by saving a month instead of .

On these numbers the money runs out at age — years short of the age you planned to. What the projected corpus actually supports is a month in today's money, against the you entered.

The projected corpus supports a month in today's money — more than you asked for, with left at .

What this means

  • The answer rests on three guesses: prices in India rising a year, medical costs , and the rupee falling a year against the . Change them under the assumptions to see how far the corpus moves.
  • The corpus figures are in the rupees of the year you retire, years from now. The monthly spending figures are in today's money.
The link holds the numbers above, so whoever opens it sees the same result. Saving keeps those numbers in your account.Nothing is stored by us.

Keep this result. An NRIWallah account saves it and sets NRIWallah up for where you live, so you don't type it all again.

Save it

Healthcare eats the plan

in your first year of retirement, from today.

It is of your budget today and at retirement — and it keeps climbing every year after, reaching by age .

Because it compounds at % while everything else compounds at %.

Abroad or in India?

at %
₹ at %

Both restated as what they actually buy in India, after the rupee's slide and Indian inflation.

The rupee's fall does not make you richer — it roughly offsets the inflation gap. Whatever advantage exists comes from the return you can earn, not the currency you earn it in.

First-year withdrawal

of the corpus, drawn in year one.

The step change on the day you land

More on the timing in moving back to India and the RNOR tracker.

AgeLivingHealthcarePensionRentDrawnCorpus left

Assumptions last reviewed . Exchange rate used: ₹ per .

Common questions


A great deal, and it is often left out of plans. After decades in the UK, healthcare has never been a budget line; in India it becomes an insurance premium, which for a couple in their sixties can run well over a lakh a year, plus whatever the policy does not cover. Many people buy cover before they return, because waiting periods for pre-existing conditions can be up to three years, and they start when the policy does. Our health insurance guide covers the options.

NRE interest is exempt from Indian tax under section 10(4)(ii) only while you count as resident outside India. When you return to live in India, your NRE accounts must be redesignated as resident accounts, or the money moved to a resident foreign currency (RFC) account, and the interest becomes taxable at your slab rate. For a retirement funded largely from NRE deposits, that is a drop in income just as you start spending.

Lower than the 4% often quoted. That rule comes from US market history and US inflation, and it fits a rupee retirement, with higher inflation and more volatile returns, poorly. Research suggests that lower first-year withdrawal rates last longer: 3.5% has held up better than 4.5% in most historical tests, and above 5% the plan depends heavily on returns. A planner can test your own figures. The calculator shows your first-year withdrawal as a percentage for this reason.

No. India has no uprating agreement with the UK, so a UK State Pension paid to someone living in India is frozen at the rate when they left, or when it started if later. Over a thirty-year retirement with 2% UK inflation it loses about half its real value. Canada, Australia and South Africa are among the other countries where it is frozen; in the US and most of the EU it rises as normal. The calculator has a checkbox for this.

Planning the move?

If the gap looks large, or you are trying to time the sale of foreign assets against the RNOR window, tell us about your situation and we’ll pass it to an independent cross-border financial planner or tax adviser (not part of NRIWallah), who may pay us a referral fee.

Something went wrong. Please try again in a few minutes, or reach us through our contact form.

Free to use. NRIWallah may receive a referral fee from the professional, never from you — how we make money.

Every rate and threshold here is sourced, dated and shown on the page — but tax rules change, and we would rather be told than be wrong. Reports go to the team that maintains the tool. If you can point at the official source, that gets it fixed fastest.

No account needed. We don't publish your email or add you to anything.

How we source and review these numbers is set out in our methodology.