IST: 00:00 PM
IST:

All NRIs

Cross-currency growth calculator

Money in India and money where you live, projected together and restated in the currency you will spend.

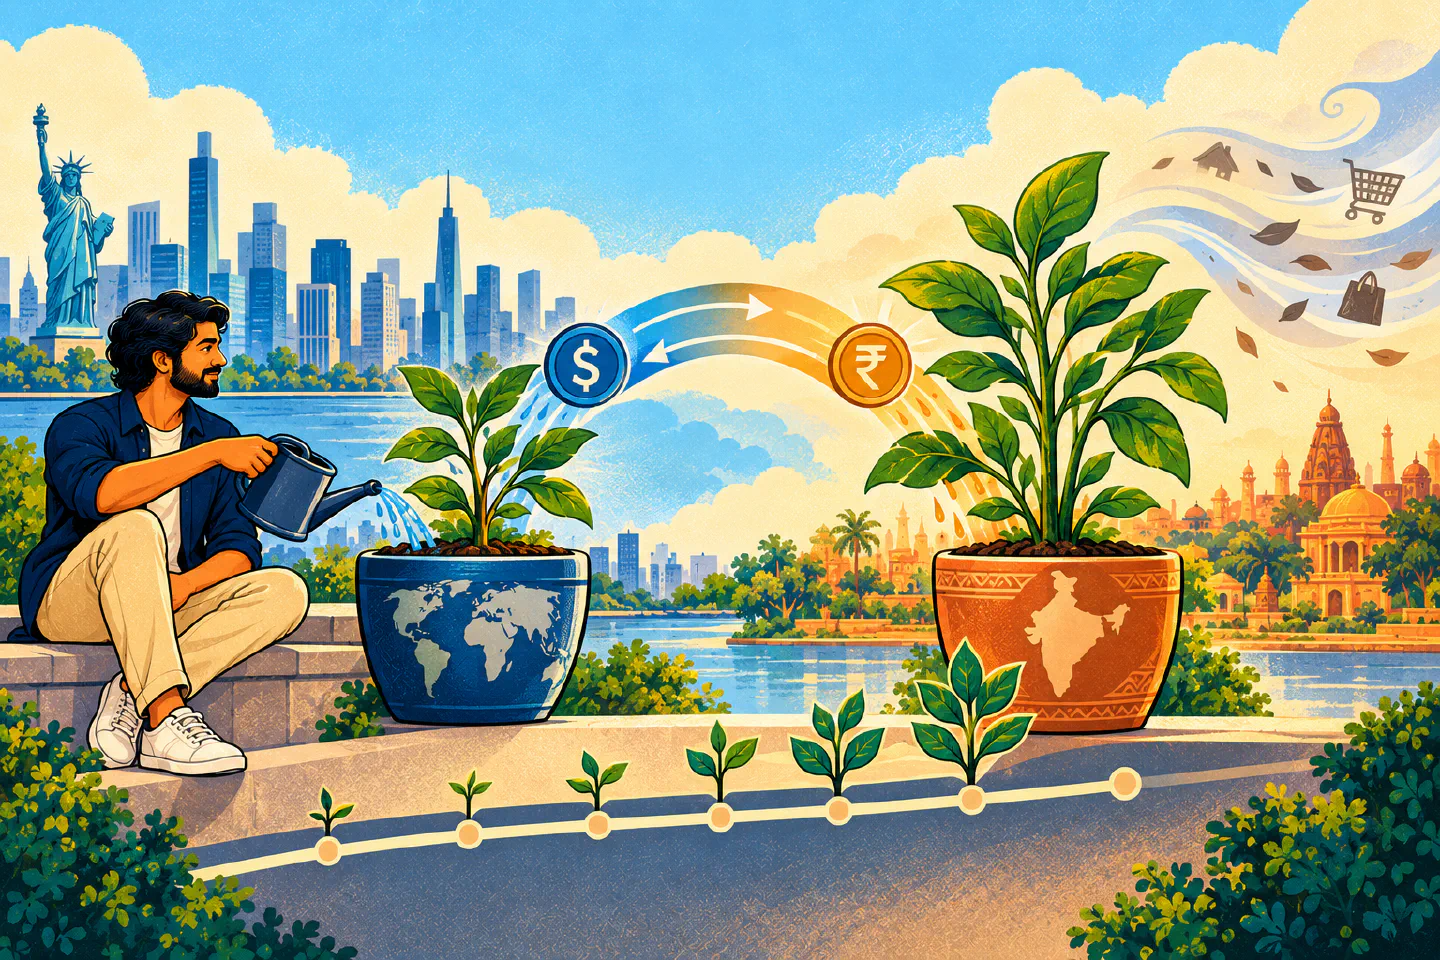
Illustration of savings in two currencies growing over time with an exchange-rate bridge between them

NRIWallah team

Updated September 2026 · 2 min read


Most growth calculators assume your money is in one currency. They split the result into what you started with, what you added and what it earned. An NRI with savings in India and abroad has a fourth part: the change in the exchange rate. Over twenty years it can be larger than the investment returns, and unlike fees it cannot be shopped around for. This calculator shows it as a separate band, at its real size.

Where you will spend the money

The calculator first asks where you will eventually spend the money, because that reverses the answer.

Take someone with ₹40 lakh in Indian mutual funds and £60,000 in a UK ISA. If they retire in Surrey, a rupee falling 3% a year steadily erodes the Indian half; over twenty years it can lose more than a third of its sterling value. If they retire in Pune, the same fall helps: their pounds buy more rupees than today, and the Indian half was never exposed. Same portfolio, same markets, opposite conclusions.

A tool that reports everything in pounds has assumed you are staying; one that reports in rupees has assumed you are going. If you do not know yet, look at both.

How much is in the right currency

The calculator also shows the share of your wealth held in the currency you plan to spend. Someone planning to retire in India with 85% of their savings in dollars depends on the dollar-rupee rate in twenty years’ time. That can be a sensible position, but it should be chosen, not the result of saving wherever you happened to earn.

Check it against your actual commitments: care for parents in India, university fees in Boston or a mortgage in Manchester are each due in a particular currency. The retirement planner covers the drawdown years, and the cost of living comparison shows what a lifestyle costs on each side.

Limits

The projection assumes steady returns and a steady currency trend; real markets do neither, and the order of good and bad years changes the outcome even when the average is the same. It leaves out tax, fund charges and the cost of moving money across the border.

It is not advice. Check that you can hold the investments you are modelling, since several Indian fund houses turn away US and Canadian residents (see the AMC eligibility checker), and remember that money in an NRO account can be sent abroad only up to USD 1 million a year.
How this works: An ordinary growth calculator splits your pot into what you started with, what you added, and what it earned. Hold money on both sides of a border and there is a fourth piece — the exchange rate moved. It can be the largest of the four, and unlike the others it is not yours to control. Tell us where the money will eventually be spent and everything is restated in that currency.

as of

Where will you spend this money?

This is not a display setting. A falling rupee is a loss on your Indian savings if you are staying put, and a gain on your foreign savings if you are moving back. Same portfolio, opposite answer.

Money in India (₹ INR)

Money where you live

The long-run average has been roughly 3% a year. In years that takes 1 from to .

In years

Your money would be worth , but in today's money that is the equivalent of .

What you put in

Investment return

Currency effect

Total value

What this means

  • A rupee falling a year costs you , or of what the investments earned. If the rupee held steady, the pot would be worth .
  • Because you plan to spend in rupees, a rupee falling a year adds when you bring the savings over.
  • Only of the pot is in , the currency you plan to spend. The rest depends on the exchange rate on the day you convert it.
  • of the pot is already in , the currency you plan to spend, so the exchange rate matters less to you.
  • Returns, inflation and the rupee are held steady every year here. Real markets and exchange rates move, so read this as a range, not a forecast.
The link holds the numbers above, so whoever opens it sees the same result. Saving keeps those numbers in your account.Nothing is stored by us.

Keep this result. An NRIWallah account saves it and sets NRIWallah up for where you live, so you don't type it all again.

Save it

Flip the question at the top of this page and this number changes sign. That is not a quirk of the tool — it is the actual position you are in.

Where the money comes from, year by year

Everything you paid in is valued at today's rate — the rate you actually got. The band at the top is the exchange rate moving.

Starting balance Added since Investment return

Bars show the whole portfolio — India and together — restated in .

What currency is your wealth actually in?

Size is not the only question. A pot that is big enough but held in the wrong currency is a bet on the exchange rate, whether or not you meant to place it.

How much does the rupee assumption matter?

The same portfolio, the same returns, three different guesses about the currency:

Over long horizons this single assumption often moves the answer more than the difference between the two return rates you chose.

Before you read too much into this. It projects constant returns and a constant rate of currency drift; real markets and real exchange rates do neither, and the order in which good and bad years arrive changes the outcome even when the average does not. Tax is not modelled here — use the SIP comparison for the after-tax India-versus-abroad question, and check the AMC eligibility checker before assuming an Indian fund will accept your money at all. Bringing a large Indian corpus out later runs into the USD 1 million a year repatriation limit.

Estimates only, and a tool rather than advice. Contributions are treated as arriving at the end of each year and are not increased with inflation. Each side is assumed to be funded in its own currency, so the cost of actually remitting money to India — the spread plus any TCS — is not deducted. Excludes all tax, fund charges and exit loads. Not investment advice. The value of investments can fall as well as rise, and past returns are not a guide to the future. Mutual fund investments are subject to market risks; read all scheme-related documents carefully.

Common questions


No one can forecast currencies, so treat any figure as a scenario. Over recent decades the rupee has fallen against the US dollar and sterling by roughly 3% a year on average, in long flat stretches broken by sharp moves, and the default of 3% reflects that. In theory higher Indian interest rates partly compensate for the expected decline, but the link is loose, especially for shares. Run the plan at 0% and at 5%: if it works at both, it is robust; if it only works at one, you are making a currency bet.

The projected total is divided by the rise in prices over the whole period, so at 3% inflation over ten years it is divided by 1.03 to the power of ten. Some calculators deflate each contribution only from the year it is made, which gives a higher figure. We use the stricter method, so our real figure can read lower than other tools for the same inputs.

No. Tax depends on the account, the asset, your residence and the treaty between the two countries, which would drown out the currency effect this tool isolates. For an after-tax comparison of India and abroad, use the SIP calculator. NRE interest is tax-free in India but usually taxed where you live; the DTAA estimator shows how relief works.

It is not deducted: each side is assumed to be funded in its own currency. In practice, sending money to India costs an exchange margin of roughly 0.3% to 2%, depending on the provider. Compare providers on the INR converter.

Contributions are held flat, the usual convention, which also keeps the projection conservative. If you expect to save more as your income rises, the retirement planner models a yearly increase alongside the drawdown years.

Every rate and threshold here is sourced, dated and shown on the page — but tax rules change, and we would rather be told than be wrong. Reports go to the team that maintains the tool. If you can point at the official source, that gets it fixed fastest.

No account needed. We don't publish your email or add you to anything.

How we source and review these numbers is set out in our methodology.