NRIWallah team
Updated
September 2026
· 3 min read
Update, 30 September 2026: the RBI closed the FCNR(B) swap window on 31 August 2026, a month earlier than first announced. New deposits no longer qualify.
From June to August 2026, Indian banks paid unusually high rates on three- to five-year FCNR deposits in US dollars, around 6% and in a few cases above 7%, against roughly 3.5% before. The cause was a temporary RBI facility, and it has now ended.
Why rates rose
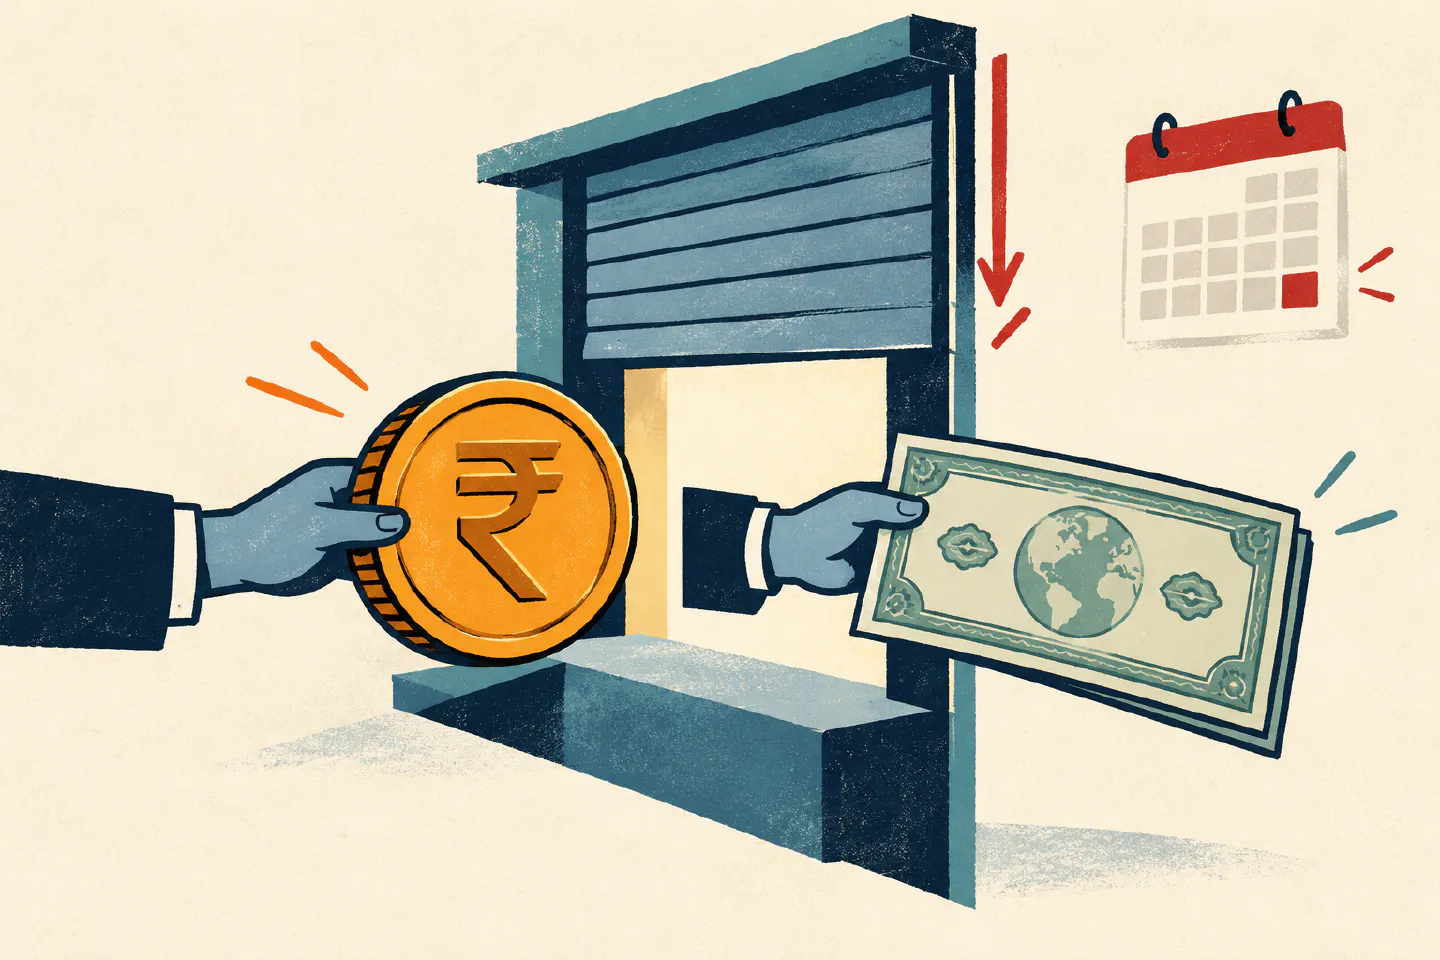
When an Indian bank takes a deposit in dollars and lends in rupees, it has to hedge the currency mismatch, and that costs roughly 3% to 3.5% a year, which comes out of the rate it can pay you. From 8 June 2026 the RBI offered banks a special dollar-rupee swap for fresh or renewed FCNR(B) deposits of three to five years, taking on much of that hedging cost, and relaxed the usual ceiling on FCNR(B) rates. Banks passed most of the saving to depositors, which is why a three-year deposit briefly paid far more than a two-year one: shorter terms were not covered.
What changed on 31 August
The window was due to run until 30 September. It raised about $73 billion by 21 August, and the RBI brought the deadline forward to 31 August. Deposits booked by then keep their rates for the full term. Deposits booked since are priced on normal terms, so expect three- to five-year FCNR rates to move back towards where they were before June, though banks will not all move at the same pace.
If you booked a deposit
- Tax where you live. The interest is tax-free in India but usually taxable in the UK, US, Canada or Australia. A UK higher-rate taxpayer keeps about 3.6% of a 6% rate; a Gulf or Singapore resident keeps it all. Our FCNR calculator shows the effect for your country.
- The lock-in. Breaking a deposit early usually costs interest, so leave the money alone if you can.
- Borrowing against it. If you need cash before maturity, a loan against the deposit is usually cheaper than breaking it.
- Deposit insurance. DICGC cover is ₹5 lakh per depositor per bank, so a large deposit is mostly backed by the bank itself.
If you are booking now
Compare the rate you are offered with an NRE rupee deposit, where the higher rate comes with currency risk, and with keeping the money invested where you live. The window’s rates applied to US dollar deposits; for pounds, euros or yen, see FCNR by currency. Borrowing to fund a deposit rarely made sense even during the window for anyone who pays income tax on the interest, and makes less sense now.
NRIWallah does not provide financial advice. Confirm current rates and terms with your bank before committing money.