NRIWallah team
Updated
October 2026
· 3 min read
Saudi remitters send a large share of their pay
Saudi Arabia levies no personal income tax on salaries, so gross pay is close to net pay. Many Indians there send a bigger share of earnings home than NRIs in the UK, US or Canada, who pay tax before anything else happens.
On a large monthly transfer, the exchange-rate margin matters more than the headline fee. A 1% spread hidden in the rate costs far more over a year than a SAR 15 charge, and “zero fees” banners are common in the Kingdom for that reason.
Reading the real cost of a transfer
Two charges sit between your riyal and your recipient’s rupee:
- The visible fee, shown before you confirm.
- The rate margin, the spread built into the exchange rate and never itemised.
The second is usually larger, and free-transfer promotions often widen it. The comparison that holds up is the total rupees received for a fixed riyal amount, checked just before you send. Our INR converter shows the mid-market rate to measure providers against.
The dollar peg
The riyal has been pegged to the US dollar at 3.75 since 1986, so SAR-INR moves only when the rupee moves against the dollar. The corridor is steadier than the Japanese yen route, where the currency itself swings. On an annual remittance of any size, small moves still add up, so a rate alert is more useful than daily timing.
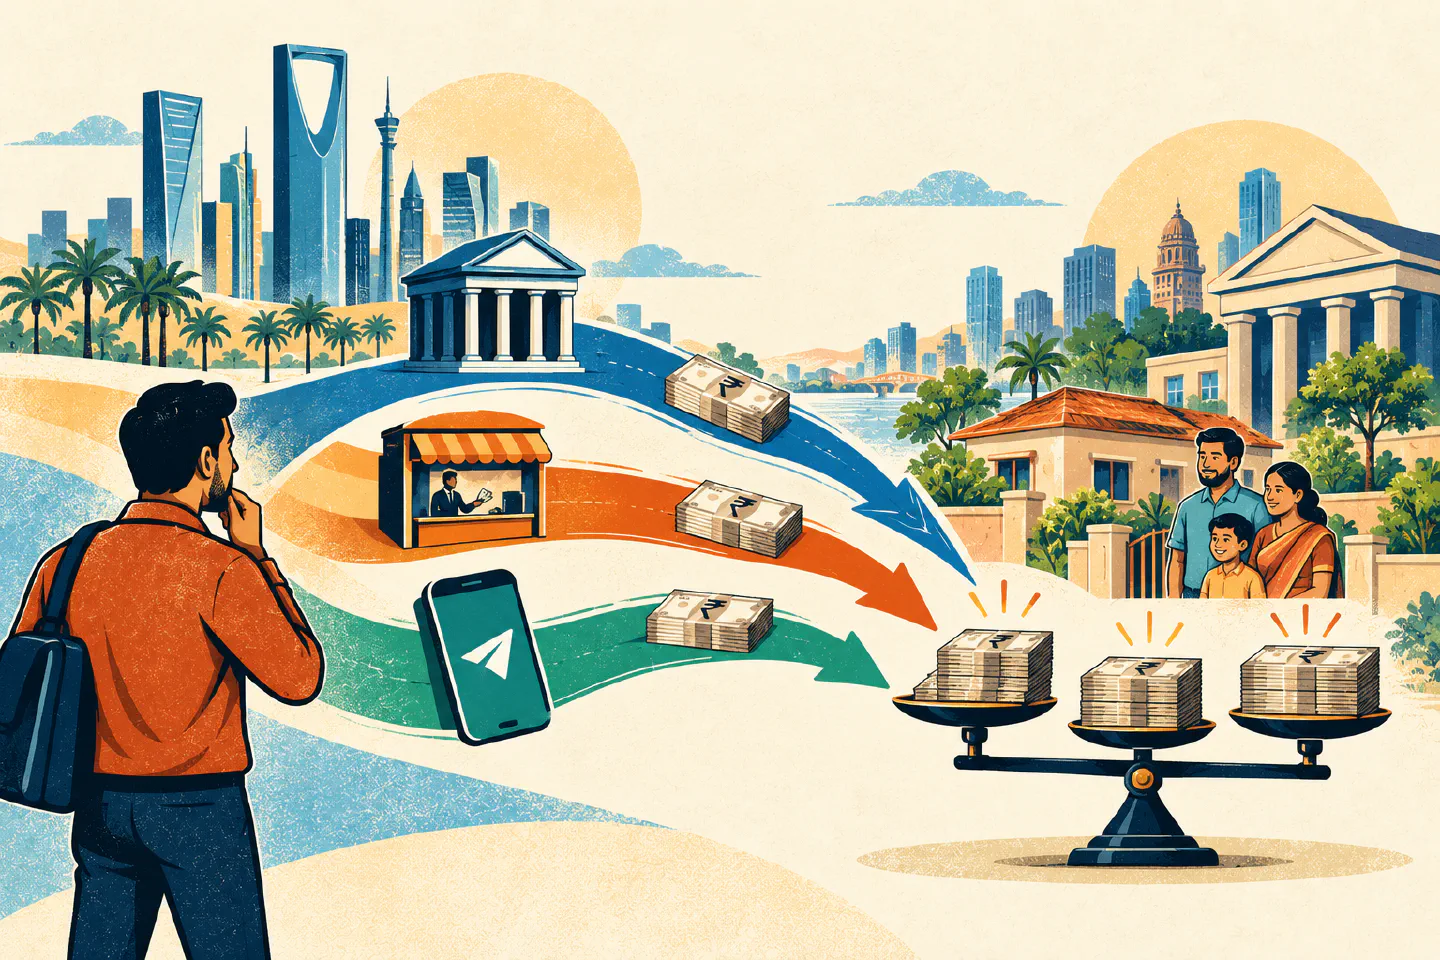
Four kinds of provider
Bank apps. Al Rajhi’s Tahweel and the other major Saudi banks run in-app international transfers. If your salary already lands there, this is the shortest path, and rates are usually mid-table.
Exchange houses. Enjaz (Bank Albilad) and similar services have wide branch networks and long hours, including in industrial areas. They suit cash-funded transfers.
Fintech wallets. STC Pay, urpay and other Saudi-licensed wallets offer simple apps and frequent introductory pricing.
International digital providers. Wise quotes the mid-market rate and states its fee separately; Remitly adds a margin to the rate and often charges little or no fee. Check that the provider serves Saudi residents before you sign up. Our Wise review and Remitly review cover how each handles NRE delivery.
Many remitters use two: a bank or exchange house for convenience, and a digital provider to check against when the amount is large.
Practical points
- Compare on salary day. Promotional rates cluster at the end of the month, so the rate you saw on the 12th may not be there on the 27th.
- Check your Iqama expiry before a large transfer.
- Where a per-transfer fee applies, one monthly transfer beats four weekly ones. Where only a rate margin applies, batching matters less.
- Keep the receipts. Indian tax filing is easier with remittance records to hand, especially if the money is being invested.
- Read the NRI banking guide before opening the receiving account, and the investment guide if the money is going to work rather than sit.
Why there is no provider table
We do not publish a provider-by-provider cost table for this corridor, because Saudi pricing changes with promotions faster than a table can be kept accurate. The AED and USD pages carry tables, and our rating methodology explains how we rate providers.
Rates, fees and promotional terms change often, so compare current numbers before you transfer. See how we make money.