NRIWallah team
Updated
October 2026
· 3 min read
A small corridor where timing matters
The Indian community in Japan is small by the standards of the Gulf or the English-speaking countries, and it is concentrated in engineering, IT and research roles around Tokyo, Yokohama and Osaka. Fewer providers compete for the corridor, so the gap between the best and worst option can be wide.
The more important feature is the yen itself.
Why the yen changes the calculation
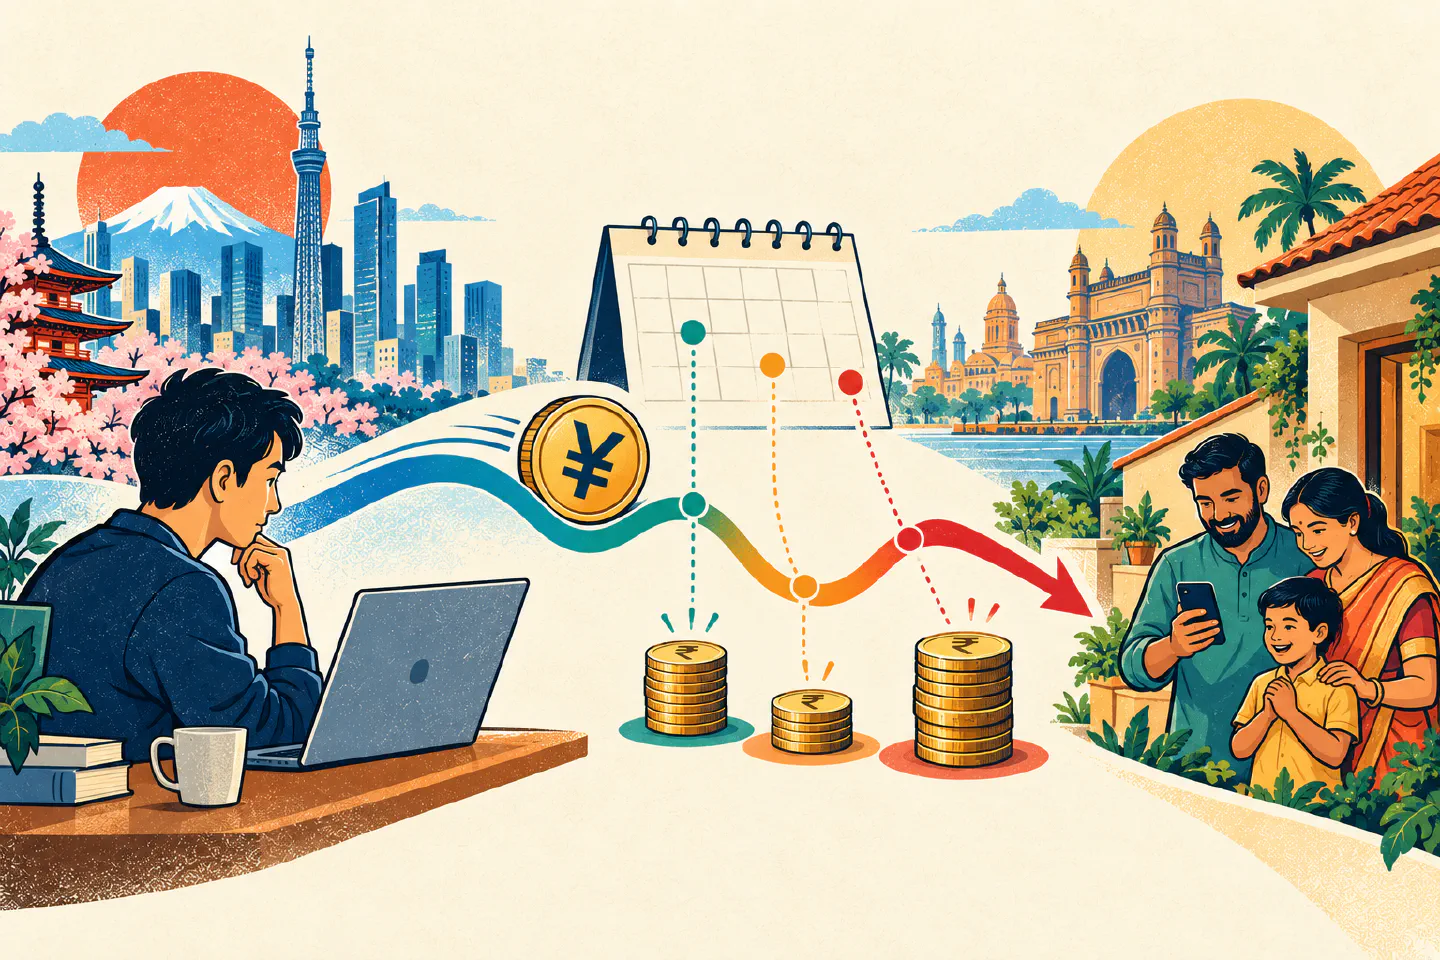
The dirham and the riyal are pegged to the US dollar, so their rupee rate follows USD-INR. The yen floats. It responds to the gap between interest rates set by the Bank of Japan and other central banks, and that gap has produced multi-year swings rather than gentle drift.
A provider’s fee advantage may be worth a fraction of a percent. A yen move over a few weeks can be worth several percent. On this corridor the question of when to send can count for more than the question of which provider.
That is not a case for speculating with your salary. It argues for setting a rate alert rather than checking now and then, and for separating money you must send this month from money that can wait for a better rate. The rate strip at the top of this site shows yen per ¥100 and its move since the last update, since the price of one yen in rupees is too small to show a trend.
Reading the real cost of a transfer
Two charges apply, as on any corridor:
- The visible fee, quoted upfront and often a flat yen amount in Japan.
- The rate margin, the spread inside the exchange rate, which is never itemised.
Japanese bank wires put the cost in the fee: a flat charge in the thousands of yen, deductions by correspondent banks in transit, and a receiving charge at the Indian bank. On a small transfer this is expensive. Digital providers charge a modest fee and a spread you can measure against the mid-market rate in our INR converter. Whatever the route, compare the rupees credited for a fixed yen amount.
The routes
Digital providers. Wise and Remitly quote the rate and the fee separately. Check each one’s current Japan to India availability and how it delivers to NRE accounts, and read our Wise review and Remitly review.
Bank wires. The major Japanese banks, such as MUFG, SMBC and Mizuho, send to India reliably. They are usually the most expensive and slowest option, but suit a very large transfer where you can negotiate or need a documented bank-to-bank trail.
Indian banks in Japan. State Bank of India operates a Tokyo branch that handles remittances to India, including for customers without an account there.
Japan Post Bank. Slower, but its branches reach well beyond the big cities.
Practical points
- Set a rate alert. On a floating currency, it is worth more than provider choice for any transfer that can wait.
- Complete identity checks early. First transfers often stall on residence-card and My Number verification, so set up the account in a month when nothing is urgent.
- Allow for correspondent-bank deductions on wires. The quoted fee is not the total cost.
- Send to NRE, not NRO.
- Keep records for both tax systems, since the DTAA only helps if you can show what was taxed where.
- Read the NRI banking guide before opening the receiving account, and the investment guide if the money will be invested.
Why there is no provider table
We do not publish a provider-by-provider cost table for the yen corridor, because the figures would need frequent checking and the corridor is thin. The USD and AED pages carry tables, and our rating methodology explains how we assess providers.
Rates and fees change often, so compare current numbers before you transfer. Nothing here is personal financial advice. See how we make money.