NRIWallah team
Updated
October 2026
· 3 min read
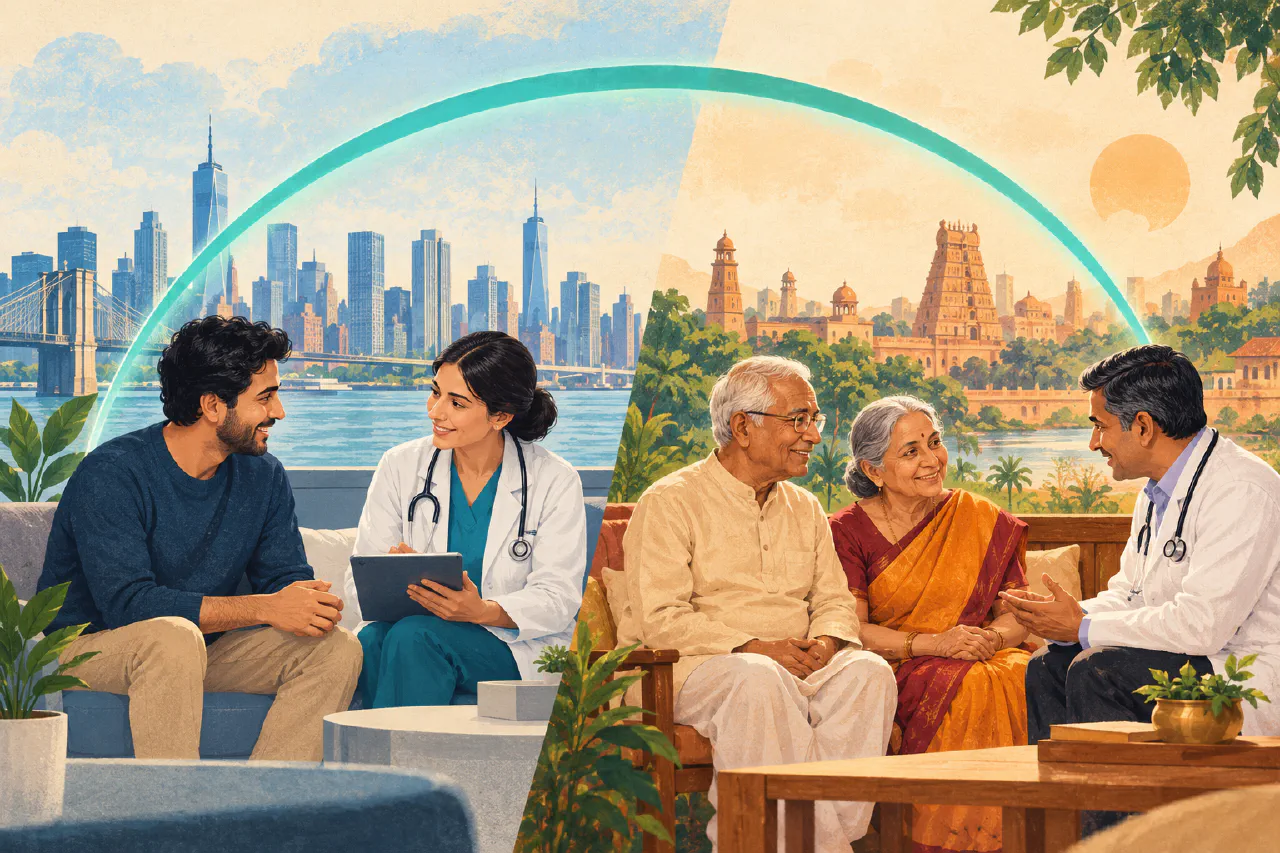
Most NRIs have two health insurance problems, and one policy rarely solves both. The first is your own health in the country where you live. The second is your parents’ health in India, where a hospital bill can fall on a sibling or a relative if nothing is in place.
Covering yourself abroad
If you live in the UK, the NHS covers you there, and many employers in the UK, US and Gulf add private cover on top. What neither usually covers is treatment in India when you visit.
There are two ways to close that gap. Travel insurance with medical cover protects you on each trip. An international health plan, such as Bupa Global or Cigna, covers treatment in most countries, India included, all year round. International plans cost much more, so they make most sense if you spend long periods in India or move between countries for work.
Covering your parents in India
Indian policies are far cheaper than international cover, but they only pay for treatment in India. That makes them the natural choice for parents who live there. Most large insurers, including ICICI Lombard, HDFC ERGO, Star Health and Niva Bupa, sell policies you can buy online from abroad. Most expect payment from an Indian bank account such as your NRE or NRO account, and some ask for a medical check at a network hospital.
It usually pays to look at cover while your parents are healthy. Anything they already have is subject to a waiting period, which for new policies sold since April 2024 can be up to three years, and premiums rise with age. International plans generally cost far more than Indian ones, so get quotes for your parents’ ages before you decide.
What to check before you buy
- Hospitals near your parents. Cashless treatment only works at hospitals in the insurer’s network, so check that the ones your parents would actually use are on the list.
- Claim settlement record. Look for an insurer that pays the large majority of the claims it receives.
- Exclusions and waiting periods. Read these before comparing headline premiums; a cheap policy that excludes your father’s heart condition for three years is not cheap.
- A base plan with a super top-up. A modest base policy plus a super top-up for large bills often costs less than a single policy with the same total cover.
- How you pay. Paying yourself, by a non-cash method, keeps the section 80D deduction available if you file in India under the old regime.
Health cover is one part of protecting a family across two countries. Our guides to life insurance and wills cover the rest, and the trip cost calculator helps you budget for visits home.